GPU-backed debt has become a market of its own. The 25 largest closed GPU-backed financings add up to $65.3 billion at headline size, undrawn commitments included, by one public tracker's count in October 2026 (AM Compute). In March 2026 CoreWeave closed an $8.5 billion facility priced at SOFR plus 225 basis points and rated A3, investment grade, for debt secured by GPUs (Wing VC). Onchain protocols now lend against GPUs too, and turn the loans into tokens.
All of it rests on hardware that the people who lent the money rarely see. This is how that hardware is checked today, and where the checks stop.
What a GPU loan is really secured by
Less by the GPUs than the name suggests. In the larger facilities the core collateral is contracted cash flow: take-or-pay contracts with the customers who rent the GPUs, ideally investment-grade ones, held together with the hardware in a bankruptcy-remote company. Amortisation is sized so the loan is repaid before the chips age out, and customers often prepay a share of the contract up front, which works like a first-loss layer for the lender.
The hardware is the second line. Wing's Chris Zeoli read the credit agreement of one recent CoreWeave facility and found no appraisal, residual value, advance rate, loan-to-value, borrowing base or remarketing terms in it at all (Wing VC). The structure leans on the contracts, and the GPUs come in only if the contracts fail.
How the hardware is checked today
At the start of the loan, the checks are documents and a visit:
- purchase invoices and the list of serial numbers that were financed;
- the hardware installed in a Tier III or Tier IV data center;
- an on-site verification by an independent third party before funds are released;
- a lien waiver from the colocation operator, so the lender's claim on the hardware ranks ahead of the data center's;
- for some lenders, a residual value warranty from a valuation firm, a floor under what the servers would sell for.
USD.AI, one of the onchain GPU lenders, describes exactly this sequence in its underwriting (USD.AI).
During the loan, the checks become financial. USD.AI monitors its loans quarterly against a minimum debt service coverage ratio of 1.15x, tested on cash actually received under the customer contracts; two quarters in breach start a cure period. Bank facilities run similar covenant tests on reported figures.
Where the gap is
Put those two lists side by side and the shape of the gap is plain: the hardware is examined once, carefully, and after that the lender watches money, not machines.
Between checks, the hardware is unseen. A quarter is a long time for a server. Cards fail and get swapped, servers move between halls or sites, a cluster sits idle while a contract is renegotiated, a model change leaves part of a fleet underused. None of it shows in a cash-flow test until it shows as missing cash.
The hardware matters most exactly when it has been watched least. The contracts carry the loan until they stop paying. Then the lender falls back on the GPUs, and has to answer at once questions nobody has been answering: are all the financed cards still there, are they the same ones, do they work, can they earn? The market behind that answer is thin. The same Wing analysis cites only $26.3 million of executed used-GPU sales over three years in the dataset it reviewed, and estimates the orderly-liquidation value of two- to three-year-old hardware at 30 to 50% of new.
Onchain, the gap is built in. A protocol can represent a GPU as a token and hold the token as collateral. A smart contract cannot look at the server. Whatever it knows about the hardware comes from someone off-chain, on a schedule.
What a live view would add
The machines themselves can answer most of those questions, continuously, if something on them is asked:
- Presence: every financed GPU is there, every minute, not once at closing.
- Identity: each card is the one on the financed list, not a substitute.
- Measurement: each card does the work its model should, measured on the card rather than read from its name.
- Availability: a server that stops answering is known within minutes, not at quarter end.
- Use: how much of the fleet is at work, set beside what the contracts say. A contract for 64 GPUs with 20 at work is worth a question before it is worth a breach.
What such a view cannot do is just as important. It does not value the hardware; that stays with valuation firms. It cannot see revenue the borrower earns elsewhere, only revenue it bills itself. And a busy GPU is not proof of a paying customer. Faking one reading is possible; keeping many readings consistent with each other every minute is far harder than writing a monthly report. It replaces trust between audits with checks. It does not replace the occasional physical audit.
Why we care about this
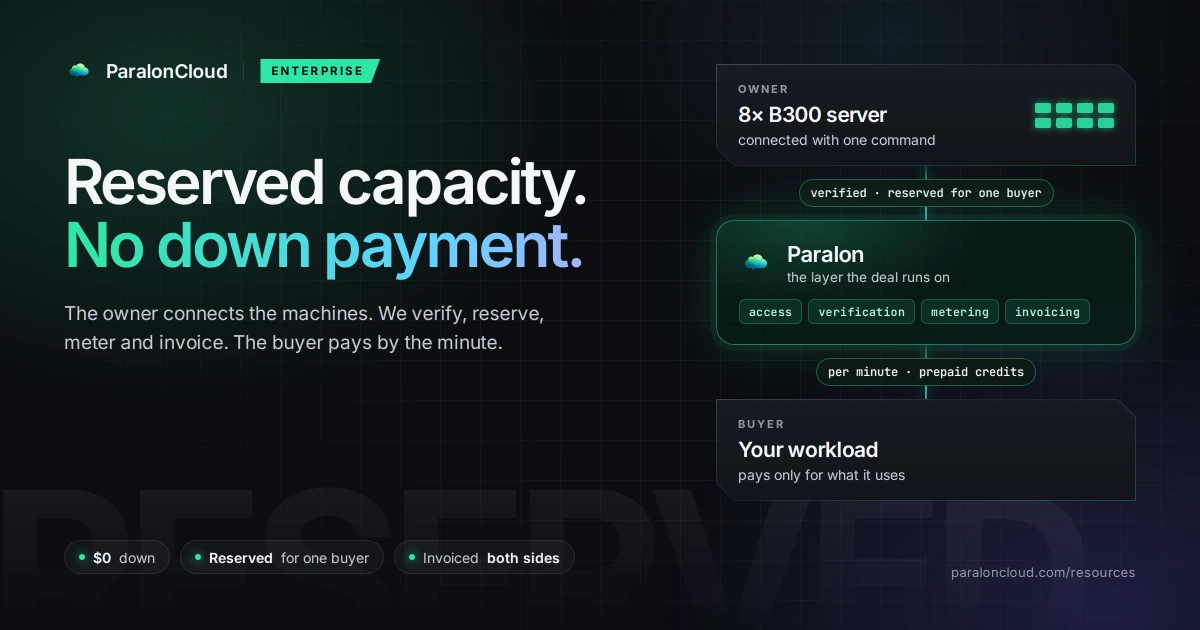
ParalonCloud runs on GPUs that other people own, so it was built not to take a GPU on its word: every card is measured before it serves, again after every reboot and daily when idle, and every server reports every minute. That is most of what a lender would want to see about its collateral.
Paralon Proof points those checks at the collateral of a loan: a live view for the lender, signed reports, alerts on the terms of the loan, and, for tokenized loans, a daily proof published onchain. The measurement is live today on every Paralon node; the collateral side is being built now with the first lenders and protocols, around what their loan terms actually test. And if a borrower stops paying, the same servers can rent on the marketplace where they stand, so the collateral earns while the lender decides.
If you lend against GPUs, or run a protocol that does, write to [email protected] with the hardware, where it runs and what your terms test.
Frequently asked questions
What is GPU-backed lending?
A loan to buy or refinance data-center GPUs in which the GPUs, and usually the customer contracts they serve, are the collateral. Neoclouds and AI infrastructure companies use it to buy hardware without raising all of it as equity. The largest facilities are now rated by credit agencies.
What do lenders actually lend against in a GPU loan?
Mostly against contracted cash flow: take-or-pay contracts with the customers who rent the GPUs, held with the hardware in a bankruptcy-remote company. The hardware matters most when those contracts stop paying, which is also when it is hardest to value.
How is GPU collateral checked during the loan?
Typically through periodic tests on the borrower's cash flow, such as a quarterly debt service coverage ratio, and through reports the borrower provides. The physical state of the hardware between those checks is largely unseen.
Why is the hardware hard to fall back on?
Because the secondary market for used data-center GPUs is thin and prices move quickly. Published estimates put the orderly-liquidation value of two- to three-year-old GPUs at 30 to 50% of new, and a lender that takes the hardware back needs a way to make it earn or sell it.
How do onchain GPU loans verify the hardware?
The protocols describe verification before the loan, such as on-site checks by a third party, a Tier III or IV data center and a lien waiver from the colocation operator, then periodic tests during it. A token can represent the hardware, but a smart contract cannot check on its own that the hardware still exists and works.